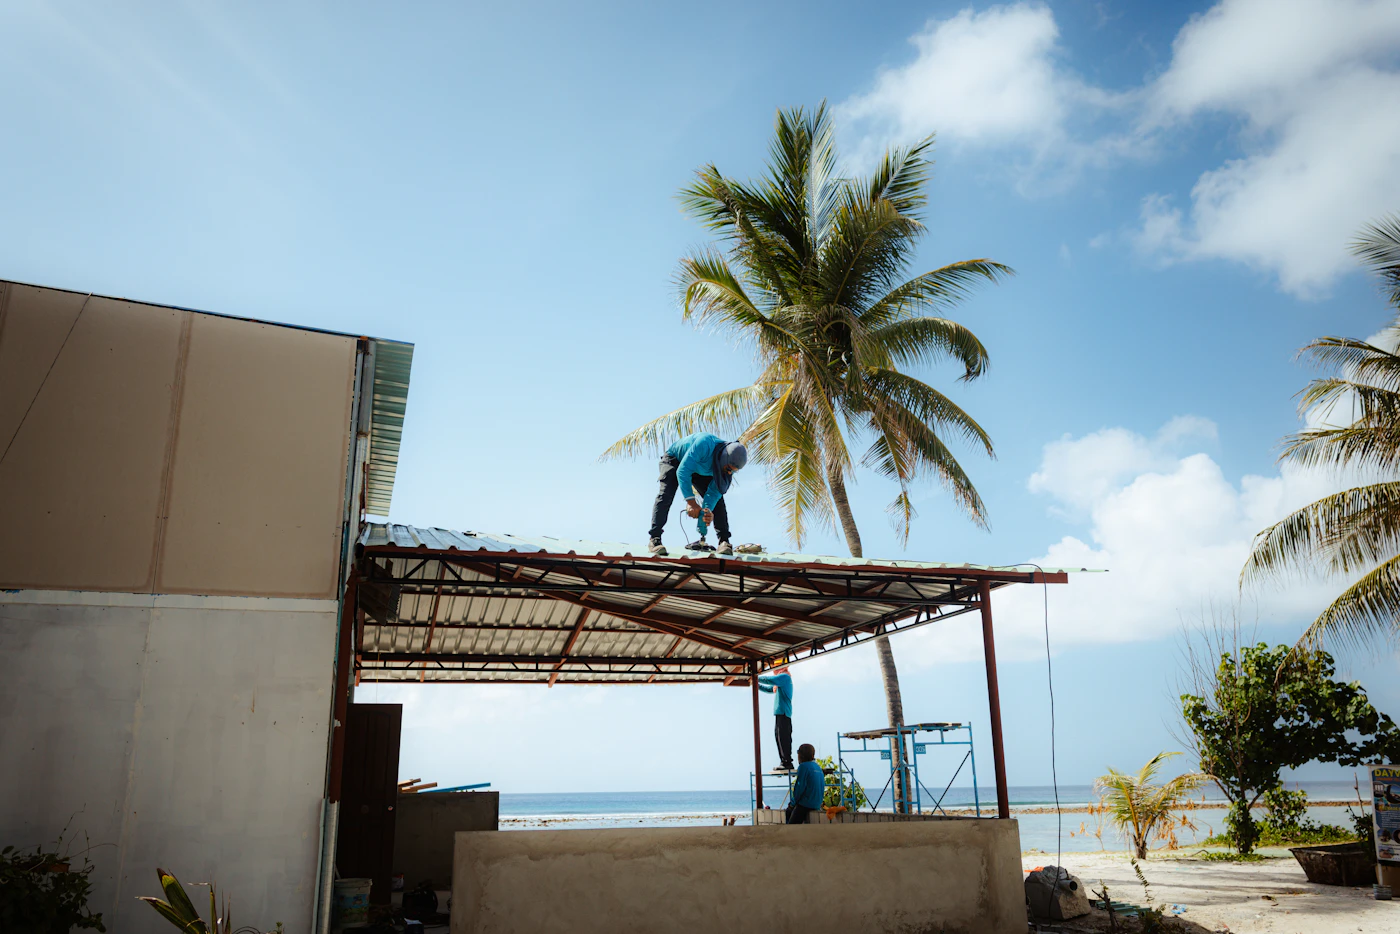
Cut, braked and hung.
General liability with completed operations, shop property and fabrication equipment, inland marine for pieces in transit, commercial auto and workers' comp for sheet metal contractors.
By Sam Alishahi · CA Insurance License #4348151 · Reviewed October 2026 · How this page is researched
A shop trade that also climbs roofs
Sheet metal contractors are two businesses on one license. In the shop you run shears, brakes, plasma tables and welders, so you need property coverage for the building contents and the machines themselves. On the job you hang duct, set kitchen hoods, bend flashings and seam metal roofing, which puts you on ladders and roofs with torches and grinders. Underwriters want to know how much of your revenue comes from each side before they price anything.
The claims that hurt are completed operations and fire. A hood that was not sealed to the duct, a flashing that lets water behind a parapet, or a duct joint that leaks into a ceiling can show up a year or two after you were paid. Hot work is the other one: Cal/OSHA's Title 8 section 4848 requires an employer to have a fire prevention and suppression procedure for welding and cutting, and insurers ask the same question in their own words.
California's Contractors State License Board puts this trade under C-43, which covers cornices, flashings, gutters, leaders, pans, kitchen equipment, duct work, chimneys, flues and metal roofing. HVAC and roofing crews often subcontract to you or hire you, so certificates with additional insured wording are part of nearly every job. I also ask whether you hold C-20 or C-39 alongside C-43, because a second classification changes the class codes and the markets that will look at you.
- Liability with completed operationsLeaks, fire from hot work and work that fails later.
- Shop propertyBrakes, shears, plasma tables and coil stock.
- Inland marineFabricated duct and panels on the truck and at the site.
- Workers' compCuts, burns, eye injuries and falls from roofs.
What underwriters will ask
Having these ready means I can go to market on the first call. The quote form asks for the same things, and anything you don’t know yet can wait.
- License: CSLB number and whether you also hold C-20 or C-39.
- Revenue split: shop fabrication versus field installation.
- Shop: address, square footage, machine list and whether you own or lease.
- Roof work: share of jobs on roofs and the heights involved.
- Hot work: your fire watch and permit routine on site.
- Payroll and subs: employees by role, subcontractor costs and loss runs.
Sheet metal contractor insurance, answered
Does general liability cover a fire started by my torch?
Fire from welding or cutting is usually a general liability claim, subject to the policy terms, but some forms add a hot work exclusion or warranty. I read the form for that wording and confirm you follow a fire watch procedure before we bind.
Is my ductwork covered while it rides to the job?
Not under the auto policy, and usually not under shop property once it leaves the building. An inland marine installation floater covers fabricated pieces in transit and at the site until they are installed and accepted.
Which license covers sheet metal work in California?
The C-43 Sheet Metal classification. CSLB describes it as selecting, cutting, shaping, fabricating and installing sheet metal such as cornices, flashings, gutters, pans, kitchen equipment, duct work, flues and metal roofing systems.
Will I need workers' comp if I work alone?
If you have employees, yes, today. Under SB 1455, California's requirement that every licensed contractor carry workers' comp regardless of employees becomes operative on January 1, 2028. I'll set the policy up before that date lands.
Do HVAC and roofing contractors ask for additional insured status?
Nearly every time, often with primary and noncontributory wording and a waiver of subrogation. I make sure those endorsements are on the policy so certificates go out the same day.
Do you offer sheet metal contractor insurance outside California?
Yes. Clients across the country send the same quote form. Sam Alishahi is licensed in 49 states and Washington, DC and places policies there directly. In Florida, where Sam's licenses are still being issued, a partner agency in your state helps in the meantime. The shopping across carriers works the same way. Rules, minimums and markets differ by state — see insurance requirements by state.
Official sources
- CSLB: C-43 Sheet Metal Contractor classification
- Cal/OSHA Title 8 section 4848: fire prevention and suppression procedure for welding and cutting
- CSLB: Senate Bill 1455 analysis (all-licensee workers' compensation operative January 1, 2028)
- California Business and Professions Code section 7125 (workers' compensation for contractors)
Insure the shop and the install.
Send your C-43 number, machine list and a rough split between shop and field work, and I'll quote liability, property, inland marine, auto and comp as one package.
Alishahi Insurance · Saman Alishahi, independent insurance broker, California License #4348151. General information, not a quote or a promise of coverage; coverage depends on underwriting and the terms, conditions and exclusions of the policy actually issued.
Tell me how to reach you. I’ll take it from there.
Takes about 30 seconds. Your application link comes by email right away, and you get an update at every step until your quotes are ready.
(877) 711-4545Answered 24/7 · CA License #4348151
Get a reminder before your renewal.
Tell me when your policy renews and I’ll email you about six weeks before, when it’s worth comparing. One email, no calls.